Finance AI change management is the work of getting accountants, analysts and controllers to actually use the agents a programme puts in front of them, and it is where many finance AI programmes quietly stall. The pilot passes, the steering committee signs off, and months later the team is still rebuilding reconciliations in spreadsheets alongside the agent. This article explains why adoption breaks down in finance specifically, how to involve the team from design rather than at go-live, how to build trust through visible controls, and how to measure real use instead of licence counts.
1. Why do finance AI programmes stall on adoption?
Most stalls have little to do with the model. They come from the way finance work is owned. A payables clerk is personally accountable for what gets paid, and a group accountant signs a reconciliation and expects to answer for it at audit. When an agent starts proposing matches or drafting journals, that person is asked to vouch for work they did not do and cannot fully see. The rational response is to check everything twice, which removes the benefit and makes the agent look like extra work.
The second cause is sequencing. Programmes are often designed by a central team, an integrator and the CFO's office, then handed to operations at go-live with a training session and a user guide. The people who know where the exceptions hide were never asked: which supplier always sends credit notes as invoices, which bank strips the remittance reference. The agent then trips over cases the team could have predicted, and every miss confirms the sceptics. Finance team resistance to AI is usually a reasonable reaction to being excluded, rather than a fear of technology.
2. What finance AI change management actually involves
Finance AI change management is less about communication plans and more about redesigning accountability. Someone has to decide, process by process, what the agent does, what a person approves, what gets escalated and who signs at the end. Until those answers are written down, staff will default to the old process and treat the agent as an optional helper. Communication still matters, but it should describe decisions already made about the work, not aspirations about a future finance function.
It also involves the roles themselves. When an agent handles routine matching, the clerk's job shifts towards exception handling, supplier conversations and fixing root causes. That is a better job for most people, but only if it is described as such, graded fairly and supported with training. Our separate piece on how roles and skills change covers the operating model in more depth. For change purposes, the key point is simple: people need to see their next role before they are asked to give up the current one.
3. Involving the team from process design onwards
Take a distribution group with entities in Dubai and Riyadh rolling out an invoice verification agent. The useful move is to put two or three experienced AP staff from each entity into the design work from the first week. They map the real exceptions, label historical invoices, and agree what a correct outcome looks like. They also become the people colleagues ask when the agent does something unexpected, which is far more credible than a message from the project office.
These AI champions in finance need protected time, not an extra role squeezed around a full close calendar. Give them authority to log defects, propose rule changes and hold back go-live for their entity if the agent is not ready. That veto is rarely used, but its existence changes how the wider team reads the programme. Choose champions for credibility with peers rather than enthusiasm for technology. A respected sceptic who is won over does more for adoption than any keen early adopter.
4. Building trust in AI agents through visible controls
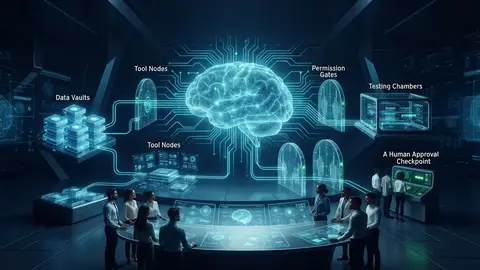
Finance people trust what they can trace. An agent that posts a match should show the documents it used, the rule or reasoning applied, how confident it was and what it would have escalated. If a reviewer cannot reconstruct the decision from the screen in front of them, they will reconstruct it manually in the ERP, and adoption stops there. Explanations need to be written in finance language, referencing purchase order lines, goods receipts and tolerance rules rather than model scores.
Clear decision rights matter just as much. Staff relax when they know exactly which items the agent may close alone, which it must route to them and what value or risk triggers a manager's review. Setting sensible escalation thresholds early, then tightening or loosening them on evidence, gives the team a dial they control. At AITHENTIC, every agent is built with a defined role, decision rights, escalation logic and a full audit trail, with people approving exceptions, and that structure works as a change tool as much as a control.
A parallel run helps, but keep it short and purposeful. Running the agent and the manual process side by side for a full quarter teaches people that the agent is optional. Agree the comparison criteria upfront, such as match accuracy and correct exception routing, review discrepancies together each week, and set a date when the manual route closes for the in-scope population. Agents that earn their place this way tend to be adopted. Agents that sit beside a permanent manual fallback rarely are.
5. How to measure AI adoption in finance teams
Licence counts and log-ins tell you almost nothing. The question is whether work has actually moved. Useful measures are operational: the share of in-scope transactions the agent processed end to end, the share of its proposals accepted without change, how long exceptions sit before a person acts, and how often staff override or redo agent work. Overrides are the most revealing signal. A rising override rate in one entity usually points to a data issue or a trust issue, and both are fixable once seen.
Measuring AI adoption also means looking for shadow processes. If the team still maintains the old reconciliation workbook, or downloads agent output to recheck it in Excel, the agent is being used as an input rather than as the process. Ask for those workbooks openly and without blame. Their existence tells you which outputs people do not yet trust, and that list becomes the improvement backlog for the next sprint, ranked by how much rework each one causes.
Report these measures to the finance leadership team alongside outcome indicators such as close duration, exception volumes or duplicate payments caught. Adoption without outcomes is activity, and outcomes without adoption usually mean a few individuals are working around the system. This is where finance AI change management earns its place on the leadership agenda: a monthly view by entity and team that shows where the programme is genuinely embedded and where it is being tolerated.
6. Training, pacing and when to slow down
Finance AI training works best when it is built around the team's own transactions rather than vendor demonstrations. Walk people through last month's real exceptions, show how the agent handled them, and let them practise approving, rejecting and correcting in a test environment that mirrors their ERP, whether that is SAP, Oracle or Dynamics 365. Keep sessions short and repeat them after the first close on the new process, when people arrive with real questions instead of hypothetical ones.
Pacing deserves more honesty than it usually gets. It is not worth expanding an agent to a second process while the first still carries heavy overrides, because the team will read expansion as the programme ignoring their concerns. Equally, an agent that has earned trust in one entity should be extended quickly, while the champions are still energised. Where the internal team lacks capacity to run this rhythm, external AI transformation consulting can hold the cadence, but ownership of adoption must stay with finance leadership.
Key challenges
- Staff remain accountable for outcomes while being unable to see how the agent reached its decisions.
- Programmes are designed centrally and handed to operations at go-live with little input from the people who know the exceptions.
- Open-ended parallel runs teach the team that the agent is optional.
- Adoption is measured by licences and log-ins rather than by how much work has genuinely moved.
- Shadow spreadsheets persist because certain agent outputs are not yet trusted, and nobody asks why.
The framework
A practical operating model for adoption is Involve, Define, Prove, Measure. Involve: respected practitioners from each entity join design from the first week as champions, with protected time and the authority to hold back go-live. Define: for each process, write down what the agent does, what people approve, the escalation thresholds and who signs off, and describe the new roles before go-live rather than after. Prove: run a short parallel run against agreed criteria, review discrepancies jointly and close the manual route on a fixed date. Measure: track straight-through processing, acceptance, overrides and exception ageing by entity and team, treat shadow spreadsheets as backlog items, and expand scope only once the current process is trusted.
How to implement it
- Nominate two or three respected practitioners per entity as champions and release time from their day job for the programme.
- Map real exceptions with those champions and use labelled historical transactions to define what a correct agent outcome looks like.
- Document decision rights, escalation thresholds and sign-off for each in-scope process before the build is complete.
- Run a time-boxed parallel run with agreed comparison criteria and a fixed date for retiring the manual route.
- Train the team on their own recent transactions in a test environment that mirrors the production ERP.
- Publish adoption measures by entity each week, including override rates and exception ageing, and act on what they show.
Frequently asked questions
What is change management for finance AI?
Finance AI change management is the work of getting finance staff to adopt AI agents as the normal way of doing in-scope work. It covers involving the team in design, redefining roles and decision rights, building trust through visible audit trails and escalation rules, training on real transactions, and measuring whether work has genuinely moved from manual processes to the agent.
Why do finance teams resist AI?
Finance teams usually resist AI because they remain accountable for outcomes they cannot fully see or control. When an agent proposes matches or journals without clear reasoning, decision rights or escalation rules, the safe response is to recheck everything. Resistance falls when staff help design the process, can trace every agent decision and know exactly which items will come to them for approval.
How do you measure AI adoption in finance?
Measure AI adoption in finance by how much work has moved, not by log-ins. Track the share of in-scope transactions processed end to end, the proportion of agent proposals accepted unchanged, override rates, and how long exceptions wait for a person. Report these by entity and team, and look for shadow spreadsheets, which show where outputs are not yet trusted.
How long should a parallel run last for a finance AI agent?
A parallel run should be as short as possible while still proving the agent against agreed criteria, often covering only a small number of processing cycles. Set the comparison measures upfront, review discrepancies jointly each week, and fix a date to retire the manual route. Open-ended parallel runs teach the team that the agent is optional and slow adoption.
Who should own finance AI change management?
Finance leadership should own finance AI change management rather than IT or an external partner. The CFO or finance director sets decision rights and pace, process owners and champions run adoption day to day, and IT and partners support integration and data. When ownership sits outside finance, success tends to be judged by delivery milestones instead of actual use.